

A sum of money arrives all at once. A bonus, an inheritance, the proceeds from a property sale. It sits in a bank account earning a small rate while the investor works out what to do with it. That waiting period has a cost, and a lumpsum investment is the way to end it. The transaction itself takes minutes. What shapes the outcome is everything decided before the money moves.
step 1: understand what a lumpsum actually is
A lumpsum investment puts a large amount into a mutual fund scheme in a single transaction. Units are allotted at the Net Asset Value (NAV) prevailing on the day the money is processed, which means the entire capital is exposed to market movements from that point forward.
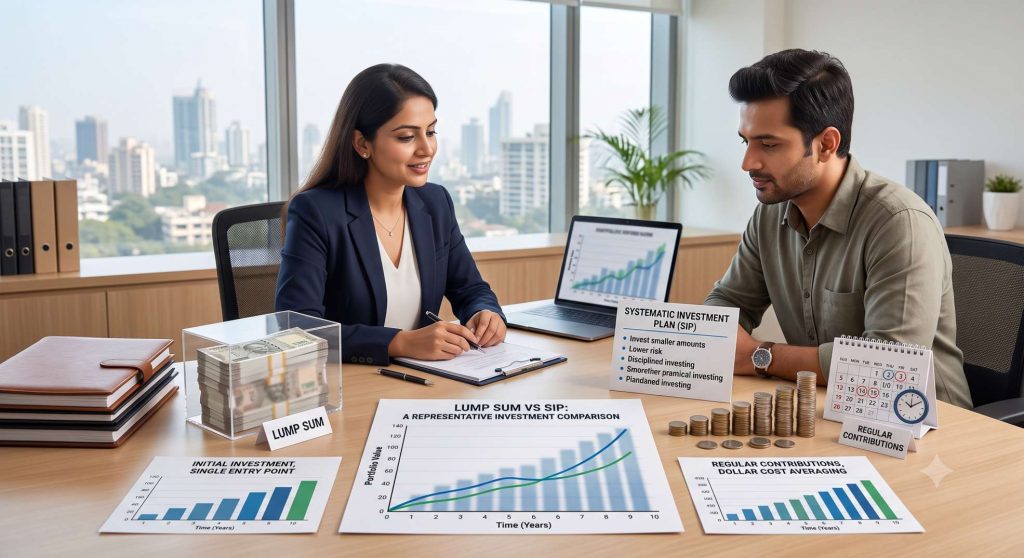
This is the mirror image of a SIP. A SIP invests a fixed amount at regular intervals, buying units at different NAVs and averaging the entry cost over time. A lumpsum commits everything at one price. If the entry point turns out well, the full capital benefits. If it turns out poorly, the full capital absorbs the drawdown.step 2: complete KYC and open an investment account
Before anything can be invested, KYC has to be done. PAN, Aadhaar, address proof, a photograph, bank details. The route can be an AMC website, a bank branch, an online platform, or a mobile app.
Once verification clears and the bank account is linked, transactions are possible. Many schemes set the minimum at ₹100. Some set it higher.
step 3: match the fund category to the horizon
Which fund to pick depends on the goal and the horizon, not on last year’s returns. Equity funds need five years or more to absorb volatility. Debt funds and hybrids sit lower on the risk curve and suit shorter horizons.
For a lumpsum, entry timing carries more weight than it does for a SIP. Money deployed into equity just before a fall will show a loss quickly, while a SIP would have kept buying through the decline. That does not make a lumpsum the wrong choice. It makes horizon and risk tolerance the deciding factors.
step 4: decide between immediate deployment and an STP
At this point, two paths diverge.
One path is immediate deployment. The full amount enters the target fund on one day. The entire capital compounds from that point. Historically, over long periods, this has produced a higher final value than phased entry, because none of the capital sits idle.
The other path is a Systematic Transfer Plan. The full amount parks in a liquid or ultra-short-duration debt fund. A fixed sum transfers into the target equity fund on a schedule. This mirrors a SIP and softens the impact of a sharp fall immediately after deployment.
STPs are common after a bonus, inheritance, or property sale. The cost is that the liquid portion earns less than equity would in a rising market, and every transfer is a taxable event in the source fund.
step 5: complete the transaction
Online is how most transactions happen now. The scheme is selected, the amount entered, the expense ratio and exit load reviewed, and payment confirmed through net banking, UPI, or a pre-linked bank account. Units are allotted only after the money transfer clears.
Direct plans, bought through the AMC website or a SEBI-registered platform, carry lower expense ratios than regular plans purchased through a distributor. No commission is built into the price.
step 6: understand the tax treatment
Fund type and holding period determine the tax. Not whether the investment was a lumpsum or a SIP.
Equity-oriented funds hold at least 65% in Indian equities. Gains on units held more than 12 months are taxed at 12.5% once they exceed ₹1.25 lakh in a financial year. Units sold within 12 months attract 20% short-term capital gains tax.
Debt funds purchased on or after 1 April 2023 are taxed at the investor’s income tax slab rate regardless of holding period. That makes them less tax-efficient than equity for lumpsum investors in higher brackets.
For STP transfers, each move out of the source fund counts as a redemption. Gains up to that date are realised and taxed according to the source fund’s rules.
step 7: monitor without reacting to daily NAV
Once the money is invested, the portfolio moves with the market. The mistakes that cost money are predictable. Redeeming during a drawdown. Switching funds based on recent performance. Losing sight of the original goal. Reviewing against the goal periodically, rather than checking NAV daily, is the more practical approach.
what retail investors should take from this
The choice between lumpsum and STP is not about which is mathematically superior. It is about matching the deployment method to the investor’s tolerance for volatility and the length of the horizon.
An investor with a long horizon and no need to touch the money can deploy immediately and let the full capital compound. An investor who would panic if the market fell 15% a month after investing is better served by an STP, even if it means leaving some return on the table.
The structure that works is straightforward. Complete KYC. Match the fund to the goal. Choose the deployment route. Hold long enough for compounding to do its work.
Frequently Asked Questions
1. What is a lumpsum investment in mutual funds?
A one-time deployment of a large amount into a mutual fund scheme. The entire amount is invested at a single NAV, and the full corpus starts compounding from day one.
2. Can I invest a lumpsum in a fund where I already have a SIP running?
Yes. A lumpsum can be made as an additional purchase in the same scheme where a SIP is active. The SIP schedule continues unchanged, and the lumpsum is invested separately at the prevailing NAV.
4. Is a lumpsum better than a SIP?
Neither is inherently better. A lumpsum gives the entire capital full compounding time from day one. A SIP averages the entry cost and reduces the impact of a single bad entry point. The choice depends on cash flow and risk tolerance.
5. How is a lumpsum investment taxed?
The same as a SIP. Equity funds held over 12 months attract 12.5% LTCG tax on gains above ₹1.25 lakh. Units sold within 12 months attract 20% STCG tax. Debt funds bought on or after 1 April 2023 are taxed at the investor’s slab rate.


