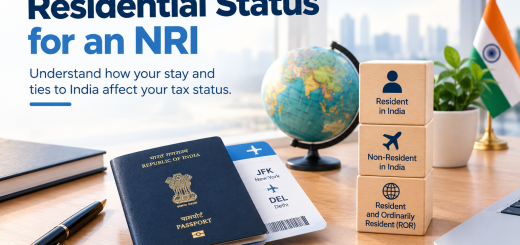
nris what decides their indian tax bill and the answer will be about nationality. it is not. residential status under section 6 of the income tax act is what matters, and it is recalculated every financial year.
that single distinction explains why a salary earned in dubai is not taxed in india while rent from a chennai apartment is. it also explains why two people with identical incomes can face very different tax outcomes depending on how many days they spent in the country. the framework is not complicated once the moving parts are clear, but the moving parts are more numerous than most people expect.
how residency is decided
physical presence is the primary test. spend 182 days or more in india during a financial year and you are a resident. there is a secondary route that catches people who spread their time across years: 60 days or more in the current year combined with 365 days or more across the previous four years. indian citizens and persons of indian origin visiting india are exempt from that secondary route and stay on the 182-day rule.
high earners face a shorter window. indian citizens and pios with indian income above ₹15 lakh become resident but not ordinarily resident, or rnor, after 120 days. rnor is a middle category, not full residency. only indian income is taxed, and foreign income stays outside the net unless it flows from a business controlled in india.
then there is the deemed residency provision, which has nothing to do with days at all. indian citizens with indian income above ₹15 lakh who are not liable to tax in any other country are treated as residents regardless of where they live. professionals based in the uae, bahrain, or qatar run into this most often.
the slabs, and the rebate nris lose
the new regime slabs for fy 2026-27 were left unchanged in the budget.
| taxable income | tax rate |
|---|---|
| up to ₹4,00,000 | nil |
| ₹4,00,001 to ₹8,00,000 | 5% |
| ₹8,00,001 to ₹12,00,000 | 10% |
| ₹12,00,001 to ₹16,00,000 | 15% |
| ₹16,00,001 to ₹20,00,000 | 20% |
| ₹20,00,001 to ₹24,00,000 | 25% |
| above ₹24,00,000 | 30% |
the old regime uses different brackets. for individuals below 60, it is nil up to ₹2.5 lakh, 5% from ₹2.5 lakh to ₹5 lakh, 20% from ₹5 lakh to ₹10 lakh, and 30% above ₹10 lakh. nris choose between the two, and the old regime still permits deductions under sections 80c, 80d, and 80e. the new regime does not. running both calculations is the standard approach.
what trips people up is section 87a. for residents, this rebate makes income up to ₹12 lakh effectively tax-free under the new regime. nris are excluded from it entirely, which means tax can become payable the moment income crosses ₹4 lakh. there is a second gap too: residents can set an unused basic exemption limit against certain capital gains, and nris cannot.
which income falls inside the net
the principle is that only income with an indian connection is taxed. the categories below are where that plays out.
nro account interest is fully taxable, with tds at 30% plus surcharge and cess. nre and fcnr interest, by contrast, is exempt and carries no tds. rent from indian property is taxed under income from house property, where nris get a 30% standard deduction for repairs along with deductions for municipal taxes and home loan interest, and tenants are required to deduct tds at 31.2% before paying. capital gains on indian assets, dividends from indian companies, and salary for services rendered in india are all taxable. foreign income, including foreign salary, foreign rent, and interest on foreign bank accounts, is not.
capital gains rates
the rate depends on the asset and the holding period.
| asset type | short-term rate | long-term rate |
|---|---|---|
| listed equity shares | 20% (section 111a) | 12.5% above ₹1.25 lakh |
| equity mutual funds | 20% | 12.5% above ₹1.25 lakh |
| property | slab rates | 12.5% without indexation |
| unlisted shares | slab rates | 12.5% without indexation |
| debt mutual funds | slab rates | 12.5% without indexation |
the finance act 2024 reworked this framework. long-term gains on listed equity above ₹1.25 lakh are taxed at 12.5% without indexation, while short-term gains on listed equity sit at 20%. property carries an extra wrinkle: nris do not get the option to choose 20% with indexation for assets acquired before july 2024, though residents do.
tds, which arrives before filing
for residents, capital gains tax is typically settled when the return is filed. for nris, tax is often deducted at source before the money reaches them. the buyer or payer deducts under section 195.
| income type | tds rate |
|---|---|
| nro interest | 30% |
| rent | 31.2% |
| long-term capital gains (property) | 12.5% + surcharge + cess |
| short-term capital gains (listed shares) | 20% |
| dividends | 20% |
surcharge and the 4% health and education cess sit on top of the base rate, and a property sale with long-term gains above ₹50 lakh can see an effective rate of 14.3%. where the actual liability is lower than the tds rate, an nri can apply for a lower or nil certificate under section 197 using form 13, but this has to be done before the payment is made.
double taxation and dtaa relief
the same income can be taxed in india and in the country of residence. india has double taxation avoidance agreements with the us, uk, canada, australia, singapore, the uae, and several others, but relief is not automatic. it must be claimed at filing, usually with a tax residency certificate and form 10f. where a dtaa offers a lower rate than the income tax act, the more beneficial provision applies.
filing obligations
an nri must file if taxable income crosses the basic exemption limit. filing is also mandatory in certain cases regardless of income, including deposits above ₹1 crore in current accounts, foreign travel spending above ₹2 lakh, electricity consumption above ₹1 lakh, or tds of ₹25,000 or more. itr-2 covers most nris with capital gains and bank interest, while itr-3 applies where there is business or professional income, including intraday trading or F&O. filing is also how a tds refund is claimed when excess tax has been deducted.
income with an indian connection is taxable, the rate depends on which regime is chosen, tds runs higher than it does for residents, and dtaa relief exists but has to be claimed rather than assumed. the 120-day rule and the deemed residency provision add complexity for high-income nris and those in zero-tax jurisdictions, while for most nris the 182-day test remains the starting point. the work is not in avoiding tax. it is in knowing which income is taxable, at what rate, and where relief applies.
Frequently asked Questions
1. what income is taxable for nris in india?
income that accrues, arises, or is received in india. this covers nro interest, rent from indian property, capital gains on indian assets, dividends from indian companies, and salary for services rendered in india.
2. what is the tax slab for nris in 2026?
new regime slabs for fy 2026-27: nil up to ₹4 lakh, 5% from ₹4-8 lakh, 10% from ₹8-12 lakh, 15% from ₹12-16 lakh, 20% from ₹16-20 lakh, 25% from ₹20-24 lakh, and 30% above ₹24 lakh.
3. can nris claim the section 87a rebate?
no. section 87a, which makes income up to ₹12 lakh tax-free for residents under the new regime, is not available to nris.
4. how is tds calculated for nri property sales?
12.5% on long-term capital gains plus surcharge and 4% cess. for gains above ₹50 lakh, the effective rate can reach 14.3%.
5. what is the 120-day rule for nris?
indian citizens and pios with indian income above ₹15 lakh become rnor after 120 days in india. nris below that income threshold follow the 182-day test.